Across manufacturing and aftermarket, the technology debate has shifted from “Should we digitise?” to “Can our platforms keep up with the business model we want?” As organisations push toward outcome-based contracts, predictive services, and integrated customer portals, traditional monolithic systems are struggling under the weight of complexity.
Author Copperberg Editorial Team | *This article was developed using a combination of human expertise and AI-assisted writing. The concept, structure, and editorial direction were defined by our team, while elements of the text were generated with the support of advanced language tools. All content has been reviewed, refined, and approved by humans to ensure accuracy, clarity, and relevance.
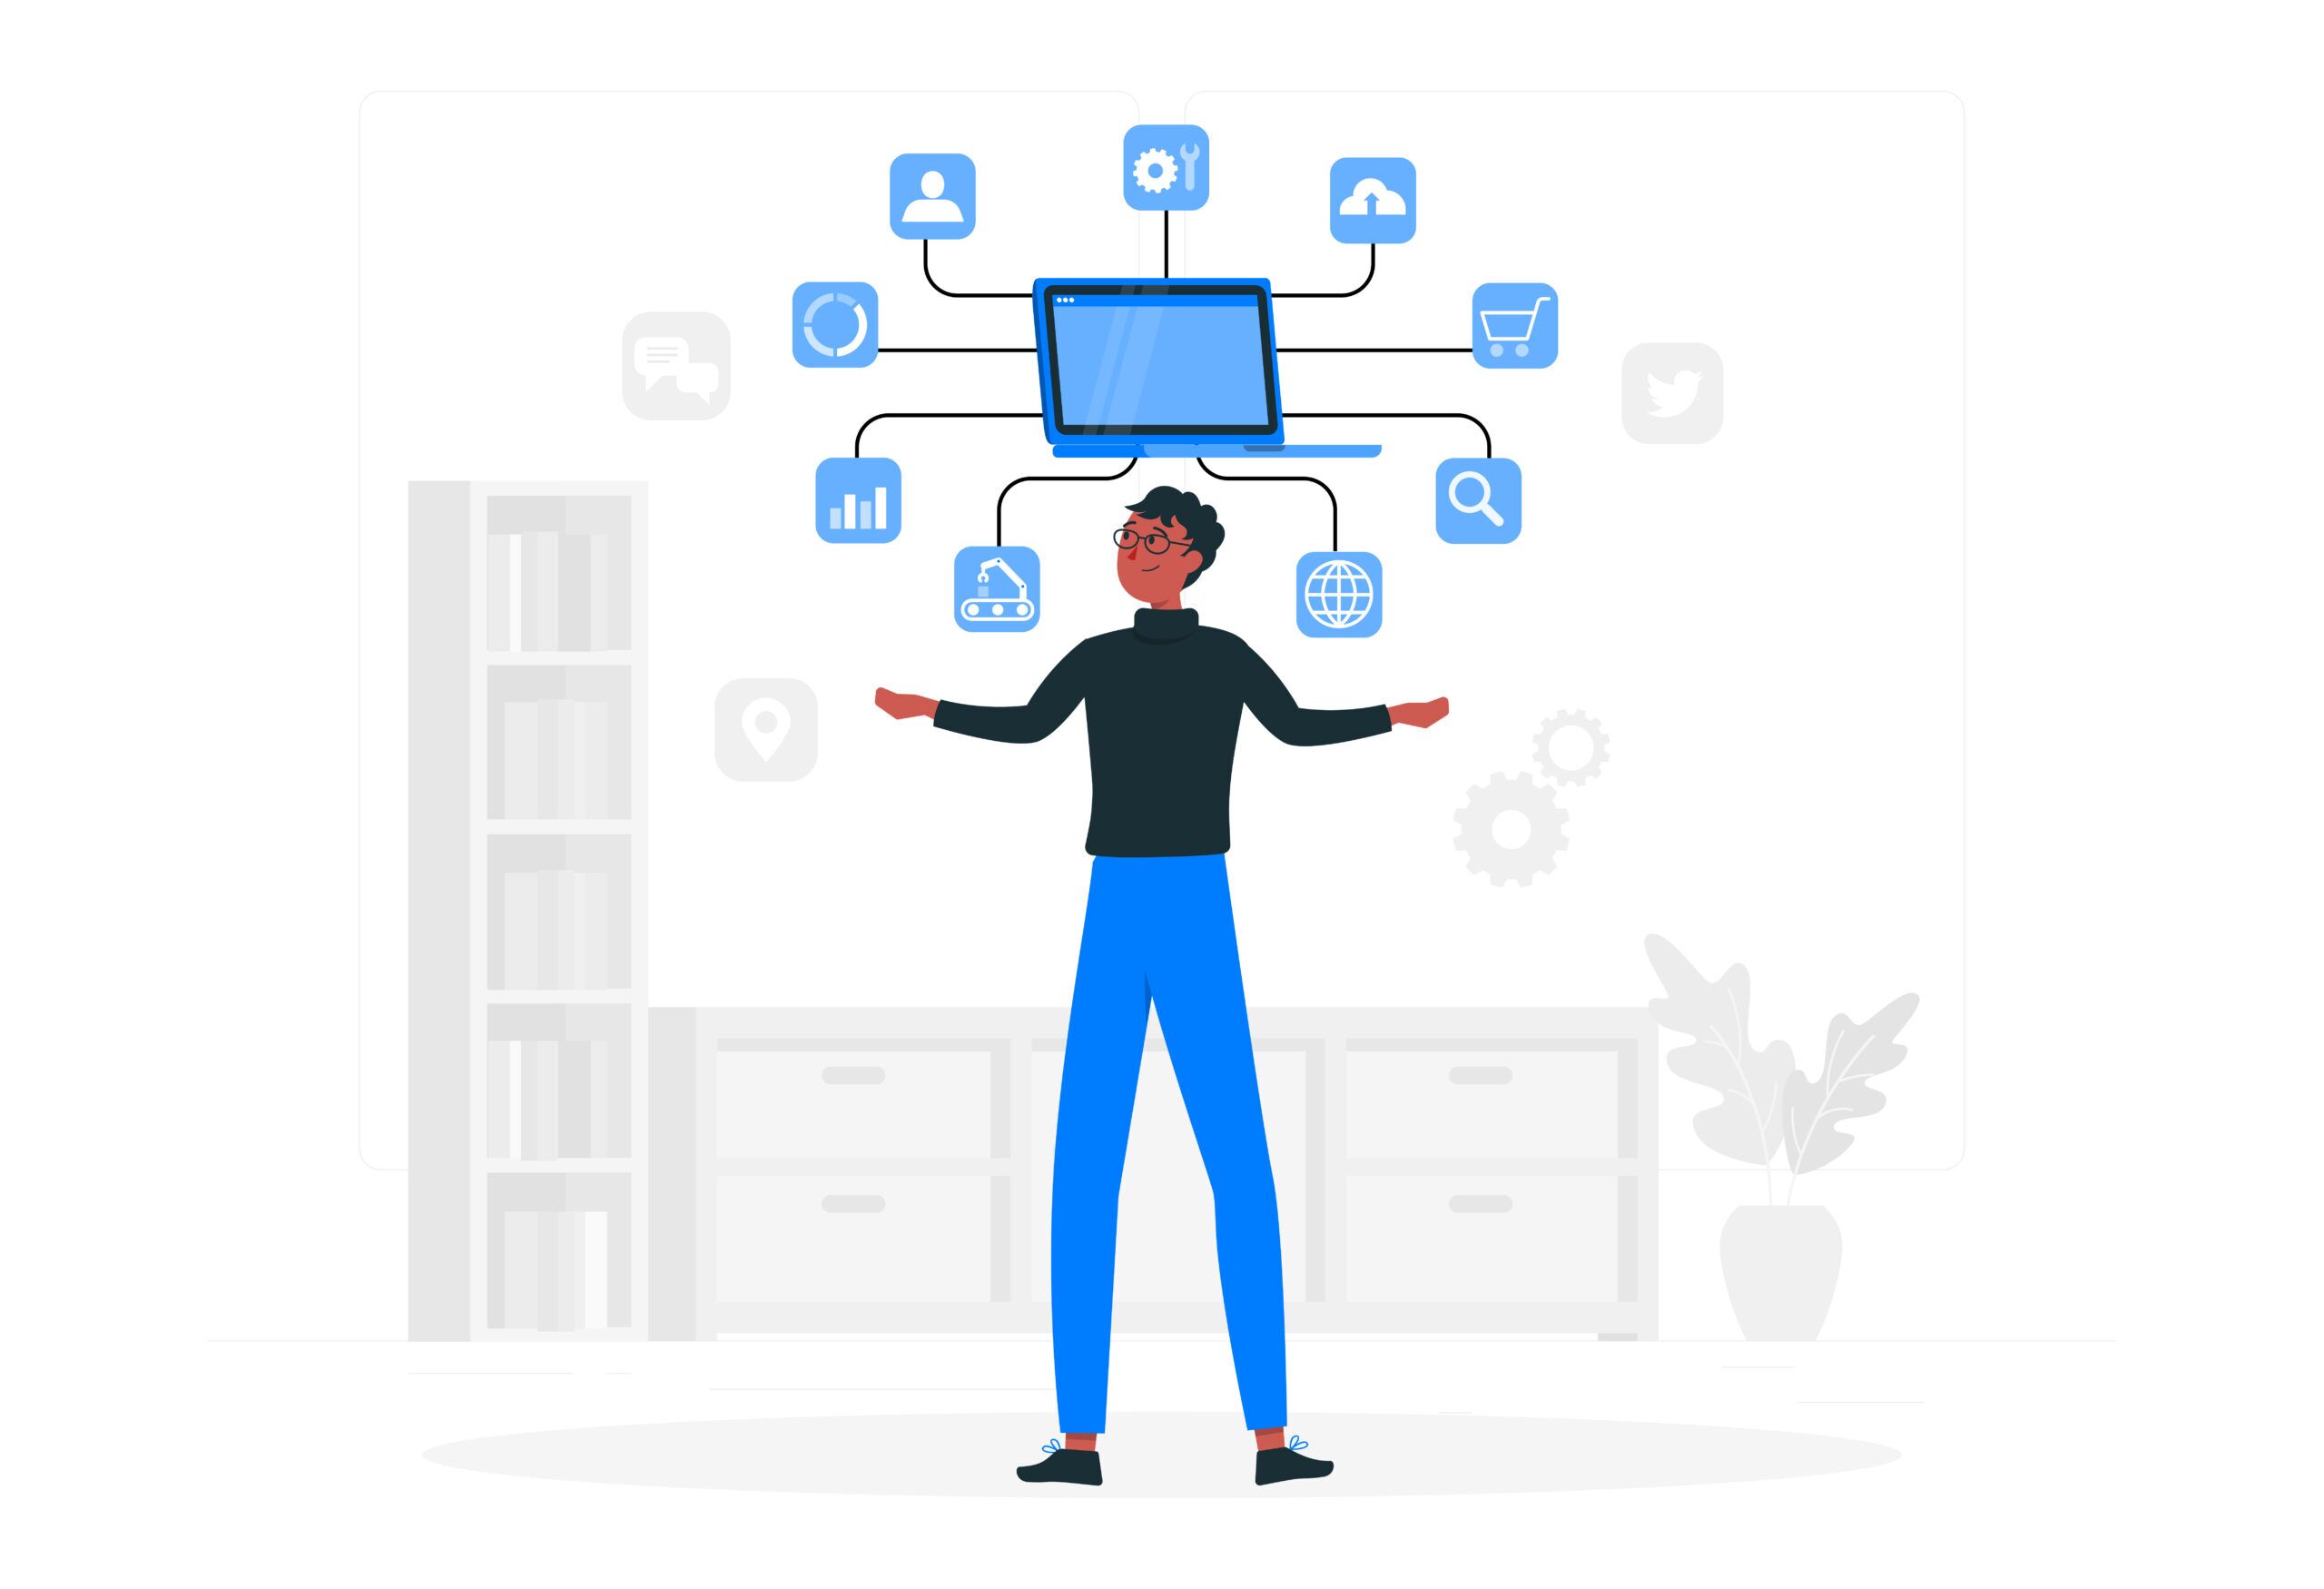
Photo: Magnific
What becomes increasingly evident is that scalability, speed of change, and resilience are no longer IT attributes; they are competitive differentiators in service. Microservices architecture is emerging as the structural answer to these demands, not as a fashionable technology choice, but as the backbone of future-ready aftermarket platforms.
From Monoliths to Modular Platforms: A Strategic Shift
For many manufacturers, current aftermarket operations sit on monolithic ERP, legacy dealer portals, and heavily customised service management systems. These platforms were designed for transactional efficiency—processing orders, logging work orders, managing inventory—not for continuous innovation or dynamic service offerings.
Microservices architecture represents a deliberate shift from this model. Instead of one tightly coupled application, the platform is decomposed into a set of small, self-contained services—each responsible for a specific capability such as pricing, warranty validation, installed base management, or predictive maintenance analytics. Each service can be developed, deployed, and scaled independently.
Strategically, this delivers three critical advantages.
First, change velocity. McKinsey has highlighted that companies adopting modular, cloud-based architectures can deliver digital features up to twice as fast as those on legacy stacks. In aftermarket terms, this means pricing teams can deploy a new dynamic pricing engine for parts without waiting for a full system release, or service leaders can pilot a subscription offer in one region without destabilising the global service platform.
Second, resilience and risk isolation. In a monolith, a fault in one module can bring down the entire application. In a microservices environment, a failure in the returns authorisation service, for example, need not impact field service scheduling or e-commerce checkout. This isolation is increasingly important as manufacturers integrate more third-party data, partner portals, and AI engines into their service ecosystem.
Third, business-model flexibility. As servitization advances, aftermarket value chains are becoming ecosystems rather than linear flows. A modular architecture allows OEMs to plug in new payment providers, predictive algorithms, or partner services without re-architecting the entire stack. At a strategic level, microservices transform the aftermarket platform from a rigid system of record into a configurable system of innovation.
Modularity as a Lever for Scalability and Differentiated Service
The advantage of microservices is not only technical; it is architectural modularity aligned with how aftermarket businesses actually operate. Most service organisations are already modular: regional service units, dealer networks, service product management, pricing, and digital commerce teams operate semi-independently. Monolithic systems force them into a one-speed world. Microservices make it possible to reflect organisational and market diversity in the platform itself.
Scalability is the clearest benefit. Instead of scaling the entire platform to support seasonal parts demand or a surge in remote monitoring data, only the relevant services are scaled out. During winter, for example, a heating systems manufacturer may need significantly more capacity in diagnostics and spare parts availability services, while keeping contract management and master data services relatively stable. Cloud-native microservices can scale automatically based on load, optimising both performance and cost.
Modularity also enables differentiated service delivery. Manufacturers can:
- Compose different bundles of services for premium vs. standard customers—such as advanced diagnostics, faster response commitments, or self-service capabilities—without duplicating entire applications.
- Configure regional variations in warranty rules, taxation, or logistics partners by adjusting the relevant microservices, instead of hard-coding regional logic into a global monolith.
- Experiment with AI and analytics in contained domains—like failure prediction for a specific asset family—by adding or swapping analytics microservices while leaving core transactional flows intact.
Accenture has noted that modular architectures and APIs are foundational for scaling digital services across complex industrial organisations, precisely because they allow new capabilities to be integrated without disrupting core processes. For aftermarket leaders, this is not only an IT principle; it is a route to faster innovation cycles and more targeted, profitable service offerings.
However, modularity introduces governance challenges. Without clear ownership, standards, and lifecycle management across services, organisations risk creating a new form of “distributed legacy”—a fragmented set of microservices that are hard to coordinate. Leading manufacturers are therefore pairing microservices adoption with strong domain-based governance, where each cluster of services (for example, “Service Contracts” or “Installed Base”) is owned by a cross-functional team accountable for roadmap, quality, and interfaces.
Integration and the Hidden Complexity of Transition
If microservices are so compelling, the question is not whether to move, but how. The greatest risk is underestimating the organisational and integration complexity of transitioning away from entrenched monolithic platforms.
The aftermarket landscape is rich in legacy: mainframe-based warranty systems, dealer management solutions, on-premise ERPs, and homegrown service portals. These systems cannot be replaced overnight, and in many cases should not be. The pragmatic path is progressive decoupling—a series of carefully sequenced steps in which specific capabilities are carved out as microservices while the monolith continues to run core processes.
A “strangler” pattern, where new microservices gradually take over functions from the legacy application, allows organisations to minimise risk and demonstrate value early. Typical starting points in aftermarket include:
- Customer and asset 360 services, fed from multiple legacy sources but exposed as a clean, consistent API for portals and mobile apps.
- Pricing engines for parts and services, which benefit from rapid iteration and experimentation.
- Predictive maintenance and IoT analytics services, often built natively in the cloud and integrated back into work-order and parts systems.
Yet every microservice added increases the need for a coherent integration fabric. API management, event streaming, and standard data models become critical. Without them, the promise of flexibility turns into a web of brittle point-to-point connections. Integration strategy must be treated as a first-class component of aftermarket transformation, not an afterthought for IT.
Equally important are operating model changes. Teams used to annual release cycles and rigid change control will need to adapt to continuous delivery, DevOps practices, and closer collaboration between business and technology. This shift often exposes capability gaps around product ownership, service design, and platform engineering. Manufacturing firms that succeed with microservices typically invest early in platform teams and clear interface contracts, so that innovation at the edge does not compromise reliability at the core.
Customer Experience: From Transactions to Intelligent, Always-On Service
Ultimately, microservices adoption in aftermarket must be justified in customer terms. The real measure is whether the architecture enables experiences and value propositions that were previously impossible or uneconomical.
Microservices directly support several pillars of modern customer experience in industrial service:
Speed and reliability of digital touchpoints. With customer-facing journeys—such as ordering a spare part, booking a field visit, or validating warranty coverage—isolated into dedicated services, uptime and performance can be managed and scaled more precisely. Outages in back-office modules are less likely to ripple into customer portals.
Consistency across channels. A unified set of microservices for pricing, availability, and entitlement can serve dealer systems, OEM portals, mobile apps, and third-party marketplaces through APIs. This reduces the all-too-common scenario in which a customer receives different answers on price or stock depending on the channel.
Data-driven engagement. Modular architectures are well-suited to embedding analytics and AI at multiple touchpoints. For instance, a recommendation service can suggest related parts or maintenance actions during checkout; a risk scoring service can flag critical assets likely to fail; an entitlement service can dynamically check coverage and propose contract upgrades. These capabilities can evolve at their own pace without disrupting core order processing.
Moreover, as manufacturers move into “as-a-service” models, customers expect continuous, proactive service rather than reactive break-fix. Microservices make it easier to orchestrate complex workflows that run across monitoring, diagnostics, dispatch, parts fulfilment, and billing—each managed by specialised services but exposed as a seamless experience to the customer.
A growing challenge for organisations, however, is experience fragmentation. If each microservice team optimises its area in isolation, customers may encounter inconsistent flows, terminology, or response times. Governance must therefore extend beyond technical APIs to experience-level standards, journey ownership, and clear service-level agreements across the microservices landscape.
Conclusion: Architecting the Aftermarket Platform of the Future
For aftermarket and service leaders, microservices should not be viewed as an abstract IT pattern, but as a structural enabler of the strategies already on the executive agenda: servitization, customer-centricity, and data-driven growth. The transition away from monolithic platforms is neither quick nor painless, but delaying it locks organisations into slower innovation cycles and rising technical debt just as competition intensifies.
The trajectory of industrial service points toward platforms that are modular, ecosystem-ready, and capable of embedding AI and analytics deeply into operations. Microservices offer the architectural foundation for this future. The strategic question is no longer whether the aftermarket can afford to modernise its platforms, but whether it can afford not to—while competitors build service capabilities that are faster to adapt, easier to scale, and harder to imitate.
About Copperberg AB
Founded in 2009, Copperberg AB is a European leader in industrial thought leadership, creating platforms where manufacturers and service leaders share best practices, insights, and strategies for transformation. With a strong focus on servitization, customer value, sustainability, and business innovation across mainly aftermarket, field service, spare parts, pricing, and B2B e-commerce, Copperberg delivers research, executive events, and digital content that inspire action and measurable business impact.
Copperberg engages a community reach of 50,000+ executives across the European service, aftermarket, and manufacturing ecosystem — making it the most influential industrial leadership network in the region.